

The legal concept of the "prudent investor" has historically acted as a financial straitjacket, forcing fiduciaries to prioritize absolute capital returns above all moral, environmental, or social considerations. If you draft a standard family trust today in an inflexible jurisdiction, your trustee is legally bound by the Uniform Prudent Investor Act to maximize yield at virtually all costs. However, modern trust investing laws are finally shifting to honor grantor intent. Most notably, the Delaware trust code explicitly amended its fiduciary standards to allow trustees to integrate ESG (Environmental, Social, and Governance) factors natively into their portfolio strategies without violating the sacred duty of loyalty.
For decades, families attempting to build ethical inheritance structures faced a profound legal hurdle: the fiduciary trap. A trustee occupying the role of wealth management for your beneficiaries lives in constant fear of litigation. If a corporate trustee sacrifices even a fraction of a percent of anticipated financial return to avoid investing in fossil fuels or weapons manufacturing, they expose themselves to lawsuits from heirs claiming a breach of the "sole interest rule." Understanding how progressive jurisdictions like Delaware have solved this liability crisis is the crucial first step for forward-thinking settlors navigating the intersection of fiduciary duty and ESG.
The Myth of the Prudent Investor vs. The Reality of Forced Yield
To grasp why the Delaware trust code ESG provisions are revolutionary, one must investigate the deep historical roots of standard trust law. Under the traditional Uniform Prudent Investor Act (UPIA), fiduciaries are governed by the strict duty of loyalty. In legal terms, this incorporates the "sole interest rule," dictating that a trustee must administer the trust strictly for the financial benefit of the beneficiaries.
Within the mahogany-lined conference rooms of institutional banks, this rule has manifested as a defensive obsession with modern portfolio theory. Because trustees can be held personally liable for sub-optimal asset management, they rely on standardized indices and broad market diversification. When a family requests that their inheritance only be invested in sustainable technology or socially ethical companies, traditional trustees immediately view this constraint as an unacceptable liability.
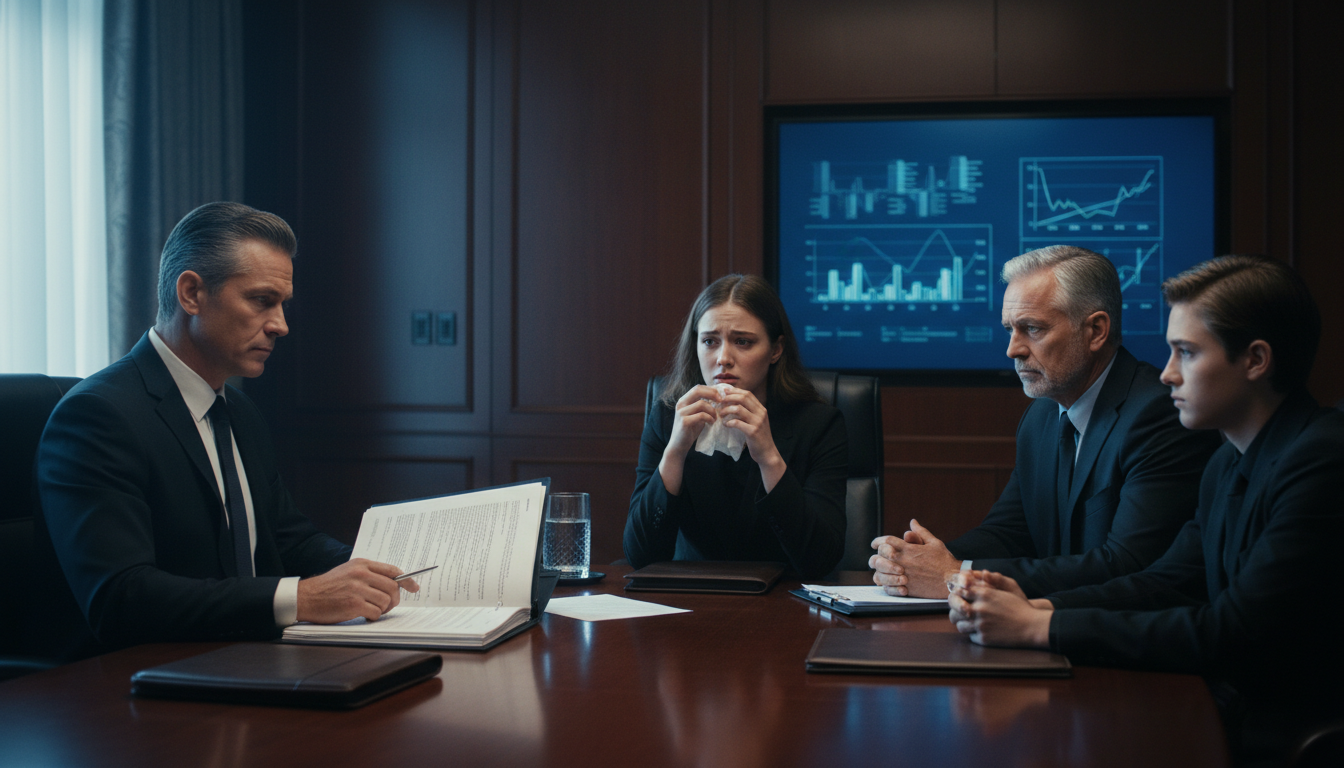
Imagine a typical estate settlement meeting. The executor sits across from the surviving children of a lifelong environmental philanthropist. The children request that the estate divest from thermal coal and heavily polluting industries, honoring their mother's life's work. The corporate trustee, consulting their compliance manual, coldly rejects the request. The trustee explains that, according to standard legal precedent, prioritizing external social benefits over absolute financial yield is a direct breach of fiduciary duty. The heirs leave the room paralyzed, realizing the legal blueprint has wholly abandoned their family’s core values.
This distinction creates a profound fracture in estate planning. The rigid legal system flawlessly transfers raw capital, but it abruptly abandons the core ethical compass of the family. According to expert legal commentary from Harvard Law, a crucial distinction exists between "risk-return ESG" (where environmental factors are weighed solely because they might impact corporate profits) and "collateral benefit ESG" (where investments are chosen for the social good). In traditional states, collateral benefit ESG is entirely restricted.
Julian’s Fiduciary Paradox: A Failure-to-Recovery Path
Consider the real-world implications through the lens of Julian, a retired architect who built his career designing carbon-neutral infrastructure. Julian successfully built an eight-million-dollar estate and spent significant legal fees establishing a generation-skipping trust for his five grandchildren. In his initial meetings, he verbally instructed his attorney that his wealth should never fund oil exploration or labor-exploitative manufacturing.
However, Julian’s attorney drafted standard boilerplate language in a conservative legal jurisdiction. Upon Julian’s passing, a large institutional bank assumed the role of successor trustee. Because the trust document fell under unmodified UPIA standards, the bank’s algorithm automatically deployed the capital into highest-yield global index funds—heavy in the exact industries Julian despised. When Julian's eldest granddaughter petitioned the bank to adjust the portfolio defensively, the institutional trust committee issued a formal denial.
"Operating under our strict duty of loyalty, this institution cannot utilize trust assets to pursue collateral social objectives that constrain diversification and risk optimal financial returns."
Julian’s legacy was trapped. The recovery for Julian's family, however, came through a complex but powerful legal mechanism: trust decanting. Working with progressive specialized counsel, the family successfully petitioned to decant the trust over to Delaware. Because Delaware law permits trusts to adopt the state’s modernized administrative statutes, the family was able to replace the corporate trustee with an agility-focused advisory committee legally protected by Delaware's updated codes. Julian’s fundamental values were finally restored to his capital.
How the Delaware Trust Code Rewrote the Rules
Delaware has long operated as the preeminent hub for sophisticated trust architecture. Recognizing the growing demand for modern trust investing laws, the state legislature addressed the ESG fiduciary trap head-on. The state explicitly modernized its prudent investor rule, creating a statutory liability shield for fiduciaries who execute value-based directives.
According to the Delaware Code relating to fiduciary duties, explicitly outlined in Section 3302(a) of Title 12, a trustee modifying investment strategies is now permitted to take into account circumstances including "the beneficiaries’ personal values, including the beneficiaries’ desire to engage in sustainable investing strategies that align with the beneficiaries’ social, environmental, governance or other values or beliefs."
This seemingly simple statutory addition is an operational earthquake for estate planning. It means that corporate trust officers no longer have to pretend that they are engaging in sustainable investing purely for "risk mitigation." They are legally cleared to pursue "collateral benefit ESG" without the threat of a beneficiary suing them for breach of loyalty over a fractional loss in comparative yield. This evolution aligns legal infrastructure with human values.
Comparing Fiduciary Models: Traditional vs. Modern Jurisdictions
The transition from strict fiduciary puritanism to values-based management is stark when evaluating the structural liabilities assumed by the trustee. The following framework clarifies exactly how jurisdictions view ESG under modern trust investing laws.
| Legal Concept | Traditional Uniform Prudent Investor Act (UPIA) | Modernized Delaware Trust Code (§ 3302) |
|---|---|---|
| Primary Investment Motive | Strictly financial risk-adjusted return under the "sole interest" doctrine. | Holistic balancing of financial return with explicit grantor or beneficiary values. |
| ESG Status | Considered "collateral benefits." Banned unless proven to lower financial risk. | Legally protected. Collateral benefits are explicitly permitted if aligned with stated values. |
| Trustee Liability | High risk of intra-family litigation if yields underperform market benchmarks due to ethics. | Strict statutory liability shield. Fiduciaries are protected when adhering to ESG provisions. |
| Flexibility | Highly rigid. Requires court intervention or unanimous beneficiary consensus to alter. | Designed for agility. Trust protectors and advisors can shift strategies via decanting easily. |
The Operational Reality of Executing an ESG Trust
While moving your trust jurisdiction to Delaware solves the legal barrier, it introduces a highly nuanced administrative challenge. How exactly does a conventional wealth manager practically measure "sustainability" or enforce environmental objectives over decades?
Consider a brief reality check facing a compliance officer assigned to a newly drafted ethical trust. If the governing document vaguely mandates "green investments," the administrative officer freezes. Does "green" mean entirely excluding tech companies that utilize heavy server loads? Does it mean investing in transition companies that are cleaning up traditional mining? Without precise definitions, a trustee cannot execute the mandate efficiently.
This is exactly why sophisticated estate administration requires a dynamic secondary layer of context. Settlors must define their exact intent, leaving nothing to abstract interpretation by corporate risk departments. While the heavy, expensive legal trust document provides the enforcement framework, the actual philosophical definitions and contextual nuances are better preserved in a dedicated digital ethical will.
To properly construct a robust estate plan that survives corporate scrutiny, one must provide their trustees with rich, undeniable context regarding ESG definitions, desired investment exclusions, and family values. This is why utilizing Cipherwill—a dedicated digital legacy platform—is becoming standard practice alongside the formal Delaware trust execution. By organizing structured digital directives, encrypted operational context, and detailed letters of wishes in an immutable vault, beneficiaries and fiduciaries receive the precise clarity needed to maneuver complex markets ethically.
Common Drafting Mistakes That Break ESG Trusts
Even within favorable legal environments, poor drafting fundamentally sabotages ethical inheritance. The American Bar Association guidelines on trust administration frequently warn that ESG clauses must be rigorously tested before implementation. Settlors routinely fall victim to a handful of critical operational errors:
- Relying on Boilerplate ESG Language: Using undefined jargon like "eco-friendly" or "socially responsible" creates paralyzing ambiguity. If terms are not tied to specific recognizable metrics, fiduciaries will default to broad, standardized indices.
- Failing to Explicitly Waive the Sole Interest Rule: Some attorneys draft ESG preference clauses but omit the critical legal verbiage actively waiving the traditional duty to maximize financial returns, essentially giving the trustee conflicting commands.
- Not Indemnifying the Trustee: If a corporate entity faces legal liability for yielding 6% instead of 8% because of ethical constraints, they will resign. Settlors must include broad exculpatory language holding the trustee harmless from financial underperformance linked directly to following the stated ESG framework.
- Confusing ERISA Laws with Private Trusts: High-net-worth settlors often confuse the Department of Labor rules (which heavily restrict ESG in retirement plans) with private trust laws. They assume ESG is legally blocked entirely, failing to leverage progressive state codes.
Implementation Checklist for an Ethical Inheritance Plan
Shifting your wealth from a purely profit-driven mechanism to an integrated legacy blueprint demands a methodical review of your current legal architecture. Use this framework to properly align your capital with your values.
- Conduct a Jurisdictional Audit: Review the prevailing law clause in your current trust. If it defaults to standard UPIA without specific statutory overrides for personal values, discuss decanting the trust into Delaware or a comparable jurisdiction.
- Define Exclusions vs. Integrations: Clearly delineate whether your approach involves negative screening (e.g., barring all tobacco companies) or positive integration (e.g., allocating 15% to clean energy startups). Precision reduces administrative friction.
- Appoint a Dedicated Investment Advisor: Delaware directed trust laws allow you to split the administrative duties from investment decisions. Nominate a specific ethical investment committee while leaving the corporate paperwork to a standard institutional firm.
- Draft an Encrypted Ethical Will: Move your nuanced, evolving societal values out of rigid legal documents and into flexible digital inheritance vehicles. Securely document the philosophical "why" behind your financial architecture so beneficiaries grasp the deep intentionality driving your decisions.
Frequently Asked Questions
Question: What exactly is the Delaware trust code ESG update?
Answer: In 2018, Delaware updated its prudent investor standard within Title 12, Section 3302 of the trust code. This crucial legal amendment specifically allows trustees to consider a beneficiary’s personal, social, environmental, or governance values when managing trust assets, without violating their primary fiduciary duty.
Question: How does ESG investing conflict with traditional fiduciary duty?
Answer: Traditional trust law enforces the "sole interest rule," dictating that fiduciaries must make investment choices purely based on financial risk and maximum return. Historically, selecting investments for ethical reasons rather than strict profit was viewed as an actionable breach of this duty of loyalty.
Question: Does the Uniform Prudent Investor Act support sustainable investing?
Answer: Under strict, unmodified UPIA interpretation, sustainable investing is only permitted if the ESG factors directly lower financial risk or increase monetary returns. It does not traditionally broadly allow for "collateral benefits" where investments are chosen solely to promote social good.
Question: Can my beneficiaries sue my trustee for poor compliance with my ESG wishes?
Answer: Yes, if your intent is poorly documented in an inflexible jurisdiction. Historically, beneficiaries are more likely to sue a trustee for lower returns caused by ethical investing constraints. Delaware’s modernized code explicitly shields trustees who faithfully follow your written ethical directives.
Question: What is a directed trust and why does it matter for ESG?
Answer: A directed trust allows the settlor to separate administrative duties from investment management. You can hire a corporate trustee for legal compliance and a separate ESG-specialized investment advisor to make portfolio decisions, shielding the administrative trustee from financial liability.
Question: How do I move an existing rigid trust to Delaware?
Answer: You can utilize a legal mechanism called "decanting," which effectively allows a trustee to pour the assets of an outdated trust into a newly drafted trust governed by modernized Delaware law. This typically requires specialized legal counsel to execute correctly.
Question: Where should I store the nuanced definitions of my ethical investment framework?
Answer: While binding directives must reside in the formal legal trust, nuanced ethical intent, dynamic framework definitions, and deeply personal letters of wishes should be hosted in a resilient digital inheritance vault to provide vital cultural context to your trustees and beneficiaries.
By Cipherwill Editorial Team, Reviewed by Cipherwill Review Board, Trust & Security Review Team
Editorial contributor: Vedant Kulshreshtha
Review contributor: Ishani Debroy