

How to Reduce the Risk of an IRS Estate Audit: A Guide for Executors
By Cipherwill Editorial Team, Reviewed by Cipherwill Review Board, Trust & Security Review Team
Editorial contributor: Vedant Kulshreshtha · Review contributor: Ishani Debroy
No executor can guarantee that an estate will not be audited. The practical goal is to file a complete, consistent return and keep records that support the values and deductions reported. The IRS uses both automated checks and employee review to identify returns that may need clarification. Careful preparation can reduce avoidable errors, delays, and follow-up questions, although it cannot eliminate the possibility of an examination.
The Reality Behind IRS Estate Audits
The IRS does not manually read every page of every estate tax return. Returns may be screened for missing information, mathematical inconsistencies, unusual valuations, and discrepancies with information reported elsewhere. The Treasury Inspector General for Tax Administration has documented challenges involving estate and gift tax return selection, valuation issues, and limited IRS resources; those findings describe enforcement constraints, not a reliable way to predict or avoid an audit. See TIGTA's report on the estate and gift tax return selection process.
When an executor files IRS Form 706, the return should be supported by records appropriate to the assets and claims involved. For example, real estate and business interests may require valuation reports, ownership documents, financial statements, and agreements. IRS processing systems evaluate what is reported on the forms and supporting schedules, not the circumstances behind them. Clear records help the executor and tax professional explain the return if the IRS asks questions.
The Paperwork Avalanche: An Executor's Challenge
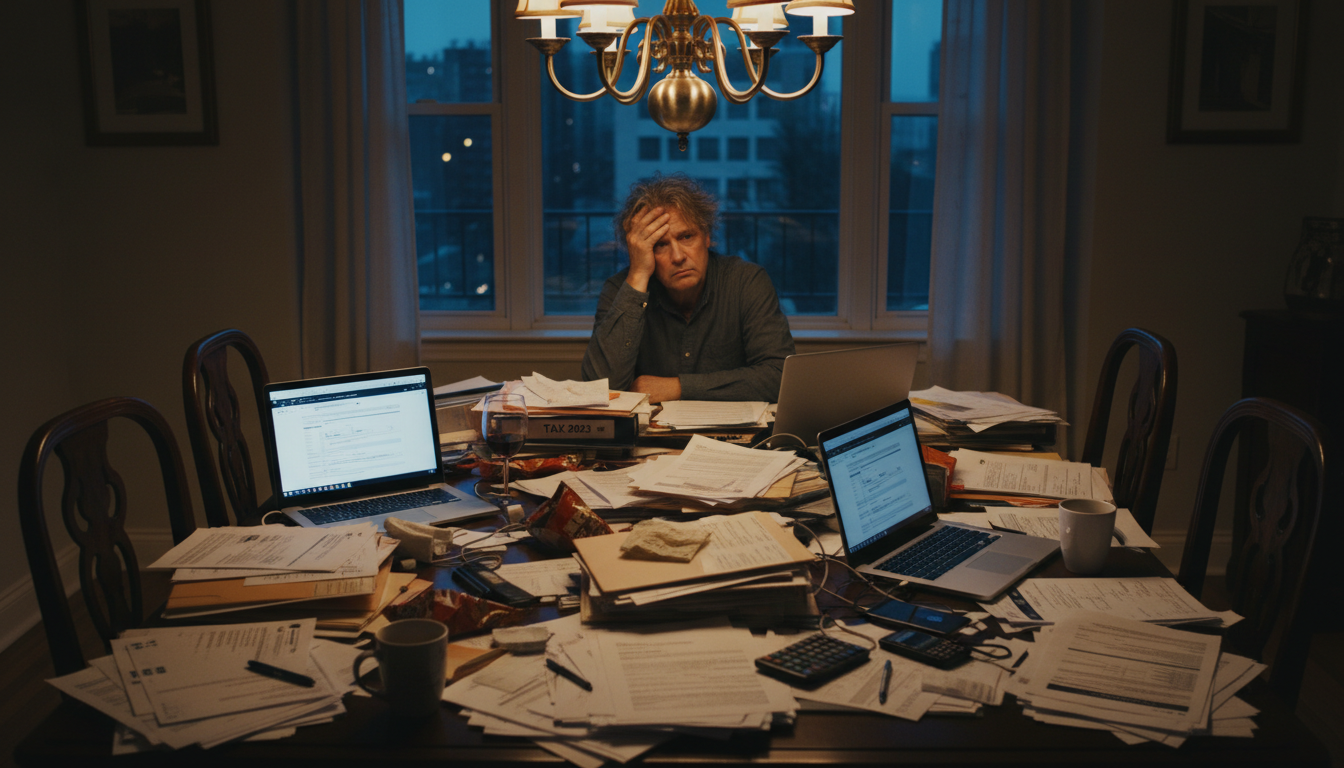
Eleanor stared at the mess across her dining room table. Her late father had been a successful commercial developer, but his estate contained fragmented records: several years of bank statements, a handwritten cryptocurrency seed phrase, and no recent appraisal of his fractional interest in a local shopping center.
The nine-month filing deadline for Form 706 was approaching, and her certified public accountant warned that the property's value could not simply be guessed. Eleanor was grieving while also trying to understand her potential responsibilities as executor. Each unidentified account or unsupported value made it harder to prepare an accurate return and respond confidently to questions from tax professionals or the IRS.
This problem is avoidable in many estates. When records are scattered among filing cabinets, online accounts, digital wallets, and business files, an executor may have to reconstruct the estate under time pressure. A current inventory and well-labeled supporting documents do not guarantee a favorable tax result, but they make accurate reporting more practical.
Common Problems That Can Lead to IRS Questions
The following issues may increase the chance that the IRS requests clarification or examines part of a return. They should be reviewed with an estate tax professional because the rules depend on the facts and the type of property involved:
- Inconsistent Form 8971 and Form 706 information: Form 8971 communicates the estate's reported value of certain inherited property to the IRS and beneficiaries. Later basis reporting should be consistent with the value reported under the estate tax rules. See the IRS instructions and guidance for Form 8971.
- Unsupported valuations: Section 2031 generally uses fair market value at the applicable valuation date. A return reporting private-company interests, real estate, or other illiquid property should retain evidence supporting the valuation, such as an appraisal, financial records, ownership documents, and relevant agreements. The Form 706 instructions explain supporting-document requirements and valuation reporting.
- Unsubstantiated valuation discounts: Discounts for lack of control or lack of marketability may be appropriate in some circumstances, but their amount must be supported by the facts, governing documents, and qualified valuation analysis. There is no universal percentage that is automatically acceptable.
- Omitted digital assets: Cryptocurrency and other digital property are still assets of the estate. The executor should identify them, determine the applicable date-of-death value, and preserve records showing ownership and valuation. The IRS provides general digital-asset guidance.
- Unreported prior taxable gifts: Prior gifts can affect the unified credit and the estate tax calculation. Executors should gather available Form 709 returns, gift records, and IRS transcripts rather than assume that no prior gifts were reported.
Private Letter Rulings: When They May Be Relevant
A Private Letter Ruling (PLR) is a written determination from the IRS National Office about how the tax law applies to a taxpayer's specific facts. PLRs are not a routine part of settling an estate. They may be considered when a significant legal question cannot be resolved through the Code, regulations, published guidance, or professional advice. A PLR generally binds the IRS only with respect to the taxpayer who requested it and the facts presented.
A ruling request can take substantial time and professional effort. User fees vary by request type and may change. For current amounts, consult the IRS Revenue Procedure guidance on user fees and ruling procedures; complex requests can involve fees exceeding $30,000, in addition to attorney and tax-adviser fees. Executors should discuss whether a ruling is necessary with qualified counsel before pursuing one.
In many estates, timely collection of records and early advice from an estate tax professional will address uncertainty more efficiently than a ruling request. A PLR is not the same as an audit and should not be treated as a general audit-prevention tool.
Organized Records Make Filing Easier
The difference between a difficult administration and a manageable one often begins before death. Without an inventory, the executor may need to search email accounts, request duplicate statements, identify ownership interests, and reconstruct the deceased person's financial history. That process can lead to incomplete schedules or estimates that later require explanation.
With a current inventory, the executor can give the CPA and attorney a starting point: account statements, deeds, business agreements, prior returns, beneficiary information, digital-asset records, and contact details for advisers. The professionals still need to verify the information and determine what belongs on Form 706, but organized records reduce the chance that an important asset or document will be overlooked.
Common Red Flags and Stronger Documentation
The examples below are not guarantees of IRS treatment. They illustrate the kinds of records that can help support a return and make questions easier to answer.
| Estate Asset Type | Potential Concern | Stronger Documentation |
|---|---|---|
| Family-owned business shares | A value is listed as pending or is based only on revenue without considering the company's financial condition, ownership rights, or transfer restrictions. | A qualified valuation report, financial statements, governing documents, and relevant buy-sell or partnership agreements. |
| Real estate | The reported value is copied from a general property-tax assessment that does not reflect the applicable valuation date. | An independent appraisal or other appropriate valuation evidence for the date of death or elected alternate valuation date. |
| Digital assets and cryptocurrency | The asset is omitted, or the estate cannot show how ownership and date-of-death value were established. | Exchange records, transaction history, valuation records, wallet information, and documentation of ownership and access procedures. |
| Prior wealth transfers | The executor assumes no lifetime gifts were reported and does not verify the deceased person's filing history. | Available Form 709 returns, gift records, account statements, and relevant IRS transcripts. |
A Pre-Filing Estate Tax Checklist
Before filing, the executor should work with a qualified tax professional to review the following:
- Create a complete inventory: List assets, policies, accounts, business interests, real estate, debts, and digital property, including the person or institution that can confirm each item.
- Gather valuation evidence: Obtain appraisals or other appropriate support for illiquid or unusual assets and preserve the assumptions used.
- Collect prior tax records: Locate relevant income tax and gift tax returns, especially Form 709 filings, and request transcripts when records are missing.
- Reconcile basis information: Coordinate Form 706, Form 8971, beneficiary statements, and future basis records so the reported values are consistent.
- Handle digital assets securely: Keep valuation and ownership information available to the tax adviser while protecting private keys and passwords. Do not place sensitive credentials in an ordinary email or unsecured file.
- Check deadlines and extensions: Form 706 is generally due nine months after death, although an extension to file may be available. An extension to file is not automatically an extension to pay.
What Good Preparation Can and Cannot Do
A complete, well-supported return may reduce avoidable correspondence and make an examination easier to manage, but it cannot prevent an audit or guarantee that the IRS will accept every reported value. The IRS may examine a return because of valuation questions, information mismatches, selection criteria, or other factors that an executor cannot control.
Start with the IRS estate and gift tax guidance, the current Form 706 instructions, and advice from an estate tax professional. Disclosure: Cipherwill offers a digital vault that can help families organize estate information for a future handoff; it does not replace legal, tax, investment, or fiduciary advice.
Frequently Asked Questions
Question: How long does the IRS have to audit an estate tax return?
Answer: The general assessment period is usually three years after the return is filed, subject to the rules in Internal Revenue Code Section 6501. A substantial omission may extend the period to six years, while certain situations, including a false or fraudulent return or failure to file, can change or remove the ordinary limitation period. A tax professional should evaluate the facts.
Question: Can a simple math error trigger IRS questions?
Answer: Yes. Addition errors or discrepancies among Form 706 schedules may lead the IRS to request clarification or correction. A processing notice is not necessarily a full field examination, but it should be answered carefully and on time.
Question: What's the difference between a correspondence audit and a field audit for estates?
Answer: A correspondence examination is handled primarily through written notices and document requests. A field examination is conducted by an IRS examiner, typically through meetings or a more extensive review of records at a location agreed upon with the taxpayer or representative. Estate matters involving complex assets or valuations may require more detailed review. The IRS's examination guidance describes the general process.
Question: Why can family-owned companies receive additional scrutiny?
Answer: Closely held businesses can be difficult to value, particularly when ownership rights, transfer restrictions, or valuation discounts are involved. The issue is not that a family-owned entity is automatically suspect; it is that the return should explain the valuation method and provide evidence supporting the reported value.
Question: What happens if a cryptocurrency wallet is not reported?
Answer: An omitted digital asset can make the estate tax return incomplete and create inconsistencies when a beneficiary later sells the asset. The estate may need to correct the return, and additional tax, interest, or penalties could apply depending on the facts. Prompt advice is important.
Question: Do I need a Private Letter Ruling to settle an estate?
Answer: Usually not. PLRs are generally reserved for unusual or unresolved legal questions and are not required for an ordinary, well-documented estate tax return. They can involve substantial user fees and professional costs.
Question: What is Form 8971, and why does it matter?
Answer: Form 8971 and its Schedule A generally communicate estate-reported values for inherited property to the IRS and beneficiaries. Those values can affect the beneficiary's basis, so accurate and consistent reporting matters when the beneficiary later sells the property.
Question: Can an organized digital vault prevent estate tax scrutiny?
Answer: No. A digital vault cannot control whether the IRS examines a return. It may, however, help a family preserve an inventory, supporting records, and instructions so the executor can give the tax professional more complete and consistent information.