

The 2026 estate tax sunset refers to the impending January 1, 2026 expiration of the Tax Cuts and Jobs Act of 2017 (TCJA) limits. When this legislation sunsets, the historic federal estate tax exemption—projected to be $13.99 million per individual in 2025—will cleanly slash in half to roughly $7 million, adjusted for inflation. To survive this multi-million dollar tax cliff wealth transfer, high-net-worth families are proactively locking in today's inflated boundaries through a Spousal Limited Access Trust (SLAT). This irrevocable trust strategy permanently shields excess capital from an automatic 40% federal tax extraction without entirely cannibalizing the family's indirect access to liquidity before the deadline.
The machinery of family wealth transfer operates strictly on timing and precise execution. For nearly eight years, affluent households have enjoyed an unprecedented harbor for generational capital. The upcoming reversion will violently alter the mathematics of estate planning. Operating under a use-it-or-lose-it mandate, family offices, legal architects, and founders are currently engineering elaborate safety mechanisms to secure current thresholds before the Congressional clock expires.
The Mathematics of the 2026 Sunset
To comprehend the severity of the 2026 estate tax sunset, one must look at the raw federal exposure. The TCJA temporarily doubled the baseline estate and gift tax exclusion. Married couples in 2025 can collectively shelter nearly $28 million from the federal government. On January 1, 2026, that combined ceiling collapses to roughly $14 million. For a family holding a $28 million estate, doing nothing guarantees that $14 million suddenly becomes taxable surplus.
At a 40% federal estate tax rate, this legislative reversion creates an unforced $5.6 million liability. This is not an abstract penalty; it is a cash obligation due nine months after the surviving spouse's death. Beneficiaries without liquid capital to satisfy this debt are frequently forced into fire sales of family businesses, private equities, and generational homesteads just to settle accounts with the Treasury.
The Private Office Reality: Marcus and the $5.6M Liability
Marcus, a 62-year-old enterprise software founder, sat in a slate-gray conference room reviewing a consolidated balance sheet with his wealth advisory team. Between his post-IPO stock, multiple real estate holdings, and a rapidly appreciating cryptocurrency portfolio, his joint estate with his wife, Sarah, hovered at $26 million.
"If something happens to both of you in December 2025, your heirs owe zero federal estate tax," his attorney explained, tapping the tablet. "If that same tragedy strikes in February 2026, your children will have to write a check to the IRS for roughly four and a half million dollars. We have eighteen months left to move twelve million dollars completely off your ledger."
For Marcus, the concept of outright giving away $12 million to an irrevocable trust for his children was deeply uncomfortable. While wealthy, tying up perfectly sensible liquidity in a completely inaccessible vault felt like an operational overcorrection. He needed a conduit that satisfied the rigid requirements of the Internal Revenue Code while preserving a backdoor to cash flow. The answer presented to him was the Spousal Limited Access Trust.
Deconstructing the Spousal Limited Access Trust (SLAT)
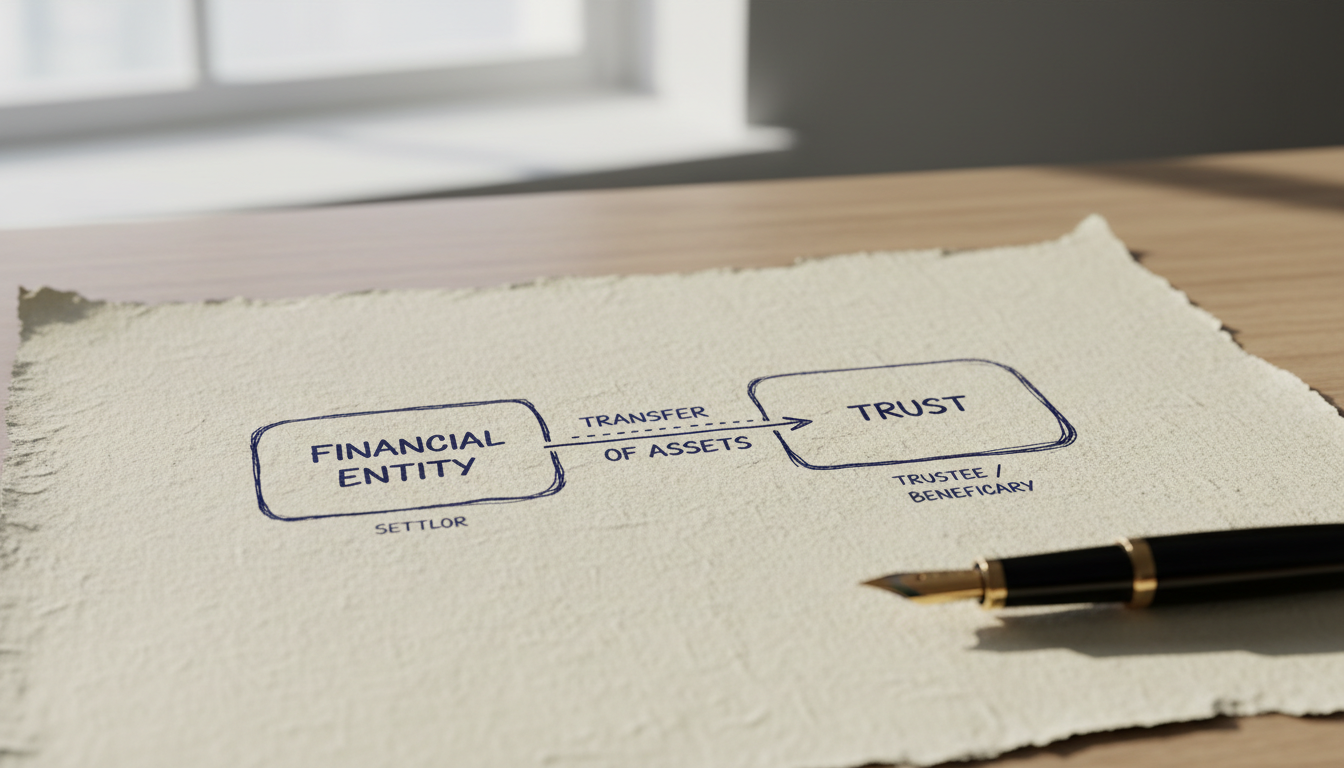
The Spousal Limited Access Trust (SLAT) strategy is undeniably the primary vehicle being leveraged by the top tier of wealth to navigate the 2026 cliff. At its core, a SLAT is an irrevocable trust established by one spouse (the Grantor) for the benefit of the other spouse (the Beneficiary), and eventually their heirs.
When the Grantor moves assets into the SLAT, they are making a completed gift. Because the 2025 gift tax limits are unified with the estate tax exclusion, funding a SLAT with $13.99 million today completely exhausts the Grantor's lifetime exemption. The magic of the architecture becomes evident immediately: not only is the initial $13.99 million permanently removed from the grantor’s future taxable estate, but all future appreciation of those assets is also immunized.
Unlike a traditional children's trust where capital is barricaded away entirely, the SLAT allows the Beneficiary Spouse to request discretionary distributions. Trustees can distribute funds based on a legally defined standard known as HEMS (Health, Education, Maintenance, and Support). Because the spouses share a life and a household, distributions to the Beneficiary Spouse naturally sustain the pair's standard of living, providing a profound psychological safety net for families nervously locking up eight figures in capital.
Strategy Comparison Matrix
Understanding how a SLAT measures against alternative strategies illuminates why it has become the default recommendation for pre-2026 planning.
| Wealth Strategy | Spousal Access to Funds | Estate Tax Shield (2026) | Asset Protection Level |
|---|---|---|---|
| Spousal Lifetime Access Trust (SLAT) | Yes, via HEMS standards directed to the beneficiary spouse | Protects current $13.99M plus all future asset appreciation | High (Shields assets from Grantor's personal creditors) |
| Direct Outright Gifting to Heirs | None. Absolute loss of control and access forever. | Protects current $13.99M plus all future asset appreciation | Moderate (Subject to heirs' creditors or divorces) |
| Status Quo (Doing Nothing) | Full, unqualified access at all times | Fails immediately on Jan 1, 2026. Only $7M protected. | None (Fully exposed to lawsuits and estate taxes) |
The Overlooked Digital Operational Reality
The financial industry routinely sells SLATs as pristine legal mechanisms. The brutal and highly overlooked reality lies in operational implementation. When you move an asset into a trust, the legal ownership entirely detaches from the Grantor. The Trustee becomes the active manager.
In practical terms, moving modern wealth into a SLAT requires transferring multi-signature hardware crypto wallets, unlisted commercial real estate deeds, private equity portals, and master cap-table credentials. The digital fragmentation of modern wealth means trustees are suddenly burdened with managing complex authentication layers and disjointed digital infrastructure. Handing a spouse or an institutional trustee a legal binder is meaningless if they do not possess verified access to the cryptographic keys or two-factor authentication loops guarding the capital.
This discontinuity is precisely why navigating these generational wealth transfers requires a dedicated continuity layer. Cipherwill enables high-net-worth families to comprehensively organize, secure, and seamlessly execute the transfer of digital accounts, critical instructions, and cryptographic assets to trusted fiduciaries conditionally. Eliminating the friction of digital credential management ensures that while the law changes ownership strictly on paper, operational access is actually preserved safely in reality.
The 2026 Estate Tax Exemption Implementation Framework
Executing a Spousal Lifetime Access Trust is an operation that takes months, not days. Waiting until Q4 of 2025 risks running headlong into bottlenecked valuations and capacity constraints among elite estate attorneys. A realistic timeline requires stringent phasing.
- Asset Partitioning: SLATs strictly cannot be funded by jointly owned assets. If a couple intends to fund the trust, they must actively partition joint accounts into separate, individually owned property first. Funding a SLAT with joint assets immediately pulls the entire corpus back into both estates.
- Liquidity Stress Testing: Financial modelers must isolate exactly how much capital the family can practically part with without artificially stressing their cash flow. Overfunding an irrevocable trust is a severe unforced error.
- Trustee Qualification: Electing the correct trustee is paramount. While a beneficiary spouse can serve as a trustee, doing so dramatically limits the types of distributions legally permitted (restricting them entirely to HEMS) to avoid having the IRS declare the control a taxable retained interest. Naming an independent trustee expands discretionary distribution capabilities.
- Legal Drafting and Floating Spouse Provisions: Documents must be built to withstand decades of demographic shifts. This includes defining clear distribution standards, integrating Trust Protectors, and establishing a "floating spouse" clause.
- Formal Re-titling and Digital Transfer: Changing deeds, endorsing physical stock certificates, and safely mapping digital authentication credentials to fiduciaries securely.
The Silent Threat: Avoiding the Reciprocal Trust Doctrine
A very common reaction for wealthy partners is symmetry: "If you fund a SLAT for me with your $13.99 million exemption, let’s build a second SLAT where I fund one for you with my $13.99 million exemption, securing all $28 million."
This invokes one of the most perilous traps in the tax code: The Reciprocal Trust Doctrine. If the Internal Revenue Service audits the structure and determines both spouses created interrelated, virtually identical trusts to circumvent estate taxes, they will "uncross" the trusts. This entirely unravels the strategy, nullifies the tax shield, and results in devastating retroactive penalties. Surviving an audit means intentionally engineering variances between the two trusts.
- Asymmetric Asset Classes: Fund SLAT A with appreciating real estate and SLAT B with private equity or life insurance.
- Varied Trustee Structures: Use a corporate trustee for one spouse's trust and an individual co-trustee arrangement for the other.
- Different Beneficiary Rights: Offer one spouse immediate broad HEMS distributions, while restricting the second spouse's distributions only to emergency health support, or incorporate different ultimate remaindermen.
- Temporal Staggering: Draft and fund the trusts months apart, potentially across different tax or calendar quarters, to disrupt the appearance of a unified, interdependent transaction.
The Secondary Scene: The Mortality Backlash
Seven months after funding Sarah's trust with $11 million of pre-IPO tech shares, Marcus was sharing a coffee with his lead advisor when a stark, chilling operational vulnerability struck him.
"Wait," Marcus said, placing his cup down. "The secondary access I have to that eleven million dollars is entirely through Sarah. What happens if Sarah passes away suddenly next year?"
The attorney gave a grim nod. "You lose all access. Instantly. If Sarah dies, or if you two divorce without specific preventative clauses, the trust corpus immediately passes down to the next generation beneficiaries—your children. You will be legally barred from taking another dollar out of that trust."
This is the mortality trap of the SLAT strategy. The Grantor’s access is strictly derivative. Upon the demise of the Beneficiary Spouse, the indirect bridge to liquidity evaporates. To mitigate this catastrophic loss of liquidity, comprehensive planners require the Grantor to purchase a life insurance policy on the Beneficiary Spouse. If the Beneficiary Spouse passes away, the death benefit pays out to the Grantor, replenishing the exact quantum of liquidity lost from the locked trust.
Critical Missteps that Unravel Wealth Transfers
Many families treat wealth preservation as an administrative exercise. However, a failure in protocol can invite aggressive scrutiny down the line. We have seen strict IRS compliance repeatedly derail otherwise flawless planning when basic mechanics are ignored.
- Ignoring the Floating Spouse Provision: Failing to stipulate that the trust benefits the "spouse of the Grantor at the time of distribution." Without this wording, divorcing the primary beneficiary legally traps the grantor's wealth with their ex-spouse forever.
- Paying Trust Taxes from the Trust: A SLAT is structured as a grantor trust. This means the individual who created it must pay all related income taxes out of their personal funds. Inadvertently paying income taxes from the trust itself actively depletes the protected assets while leaving unprotected assets in the taxable estate.
- State-Level Disconnects: Relying entirely on federal guidelines while ignoring state-level estate tax thresholds. Families moving to states like New York or Massachusetts must run secondary state-based calculations to shield assets comprehensively.
- Inadequate Credential Verification: Transferring alternative digital assets without verifying trustee login access leaves wealth entirely stranded if the Grantor suddenly becomes incapacitated.
The 2025 Year-End Cutoff Strategy Plan
For families rushing to outpace the sunset, execution over the next few quarters dictates generational outcomes. Here is the framework guiding top wealth managers.
- Audit current net worth including illiquid assets, unvested equites, and long-term crypto appreciation estimates to gauge immediate federal exposure.
- Retain a qualified valuation appraiser to deeply discount Family Limited Partnerships (FLPs) or LLCs prior to gifting them into the trust.
- Sever selectively chosen joint banking or brokerage accounts to construct purely separate property environments to fund the SLAT seamlessly.
- Consolidate instructions for key digital authentication measures securely via encrypted infrastructure so trustees are not burdened with cold trails during crises.
- Verify Generation-Skipping Transfer (GST) tax exemptions are correctly allocated on IRS Form 709 (United States Gift Tax Return) to shield the funds indefinitely.
Frequently Asked Questions
Question: What happens to my estate tax exemption in 2026?
Answer: Unless Congress passes overriding legislation, the historic limits established under the TCJA will dramatically reset. A single individual's federal estate and gift tax exemption will drop from approximately $13.99 million in 2025 to around $7 million automatically on January 1, 2026, forcing a larger segment of middle-wealth and high-net-worth assets into the 40% taxable bracket.
Question: What is a Spousal Limited Access Trust (SLAT)?
Answer: A SLAT is an irrevocable trust established by one person for the primary benefit of their spouse. It utilizes the current elevated lifetime gift tax exemption to permanently transfer wealth out of the creator's taxable estate while maintaining indirect access to the funds through discretionary distributions made to the beneficiary spouse.
Question: Can both spouses create SLATs for each other?
Answer: Yes, but it requires extreme caution to avoid the Reciprocal Trust Doctrine. If the Internal Revenue Service dictates the trusts are functionally identical and created simply to avoid taxes, they will uncross them and nullify the tax benefits. The trusts must feature deliberately different terms, assets, trustees, and operational timings.
Question: What happens to a SLAT if the couple divorces?
Answer: If standard boilerplate language is utilized, the ex-spouse retains full beneficial rights to the trust, essentially locking the original creator out of their own transferred wealth. To prevent this, estate planners aggressively advocate for a "floating spouse" provision, redirecting trust benefits strictly to whomever the grantor is legally married to at any given time.
Question: Does establishing a SLAT reduce the 2025 gift tax limits?
Answer: Yes. The federal estate tax and the lifetime gift tax use a unified exemption ceiling. Any large dollar amounts you permanently gift into a SLAT while you are alive will directly subtract from your total lifetime exclusion limit. Securing the limit now utilizes it before it fundamentally disappears during the upcoming sunset.
Question: Can a SLAT hold digital assets and cryptocurrency?
Answer: Absolutely, but transferring complex digital architectures requires nuanced stewardship. Legal title changes instantly, but trustees require secure operational handoffs of hardware wallets, seed phrases, and multi-signature approvals to actively manage capital. Without robust digital continuation systems, alternative digital assets locked in a trust become technically inaccessible orphans.
Question: What if the beneficiary spouse passes away before the grantor?
Answer: If the beneficiary spouse dies, the grantor's indirect legal access to the trust assets immediately terminates. The assets will legally cascade down to the remainder beneficiaries, usually the children. Wealth advisors commonly require the grantor to hold an equivalent life insurance policy on the spouse to inject matching liquidity back into the estate if disaster strikes.
Question: Could Congress stop the 2026 estate tax sunset?
Answer: Yes, Congress has the authority to permanently extend current thresholds, alter limitations, or draft new comprehensive legislation entirely before year-end 2025. However, predicting political cohesiveness remains highly volatile, promoting proactive estate protection rather than hoping for a favorable legislative gridlock outcome.
By Cipherwill Editorial Team, Reviewed by Cipherwill Review Board, Trust & Security Review Team
Editorial contributor: Iraan Qureshi
Review contributor: Tavish Bhonsle