

If you established an irrevocable trust benefiting your spouse before a marital separation, you might be walking into a financially devastating trap. Due to the Tax Cuts and Jobs Act (TCJA) of 2017, the quiet repeal of Internal Revenue Code (IRC) Section 682 means that the original grantor of a trust is now legally required to pay federal income taxes on trust distributions made to an ex-spouse. We will explain how the federal "spousal unity rule" forces you to pay phantom income taxes for your ex, the operational disasters this creates during divorce settlements, and how to audit your estate documents to neutralize these liabilities before negotiations begin.
The Anatomy of the Trap: David’s Spousal Lifetime Access Trust
The severity of this tax law change is best understood when it crashes into reality. Consider David, a 55-year-old commercial architect who established a Spousal Lifetime Access Trust (SLAT) in 2014. At the time, estate planners aggressively recommended SLATs as an elegant way to remove appreciating assets from a taxable estate while allowing the grantor’s spouse indirect access to the funds.
Fast forward to 2022. David and his wife, Elena, finalize their divorce. The marital settlement is tense but complete. The SLAT, being an irrevocable entity holding several commercial properties, remains intact. Elena continues to receive rental income distributions from the trust as its primary beneficiary.
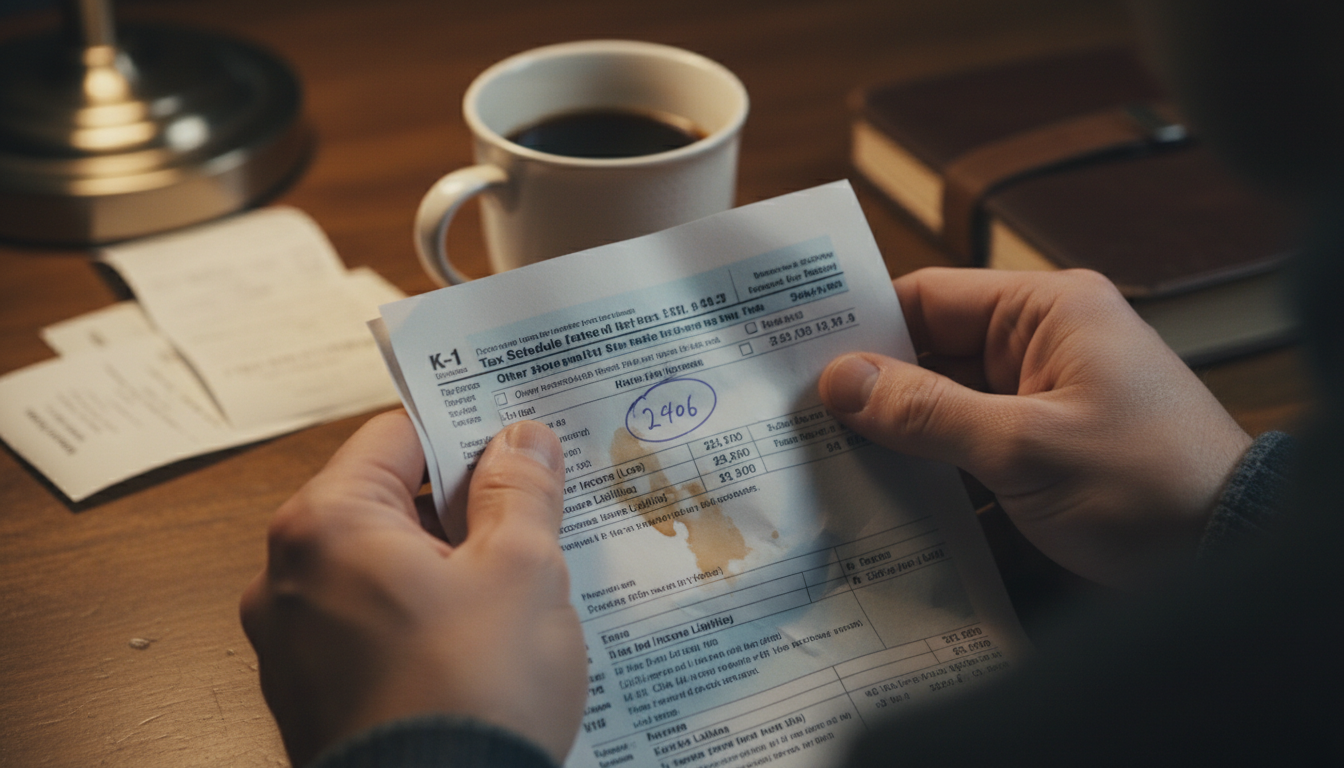
Then came mid-March of 2023. David sat at his kitchen table, sorting through his tax documents. He opened an envelope from the trust's administrative CPA expecting standard paperwork. Instead, he pulled out a Schedule K-1 reporting $180,000 in taxable income. David froze. He hadn't received a single dollar of that money; the trust had distributed the entire $180,000 to Elena. Yet, according to the IRS, David owed roughly $66,000 in federal income taxes on cash his ex-wife was currently spending.
This scenario is not an administrative clerical error. It is the direct, intended outcome of current federal tax law for anyone who failed to adapt their estate plan to post-2017 regulations. The concept of splitting a financial gift into a Spousal Lifetime Access Trust without projecting divorce consequences has become one of the most dangerous wealth-management oversights of this decade.
Understanding IRC Section 672(e) and the Spousal Unity Rule
To comprehend why David is trapped, we must look at the mechanics of grantor trusts and how the government defines a marriage for tax purposes. A trust is classified as a "grantor trust" if the creator retains certain powers or if the trust income can be distributed to the grantor or the grantor's spouse. When a trust has this status, the trust itself does not pay income tax. Instead, all income passes directly to the original grantor's personal tax return.
Historically, IRC Section 682 served as an emergency brake during a divorce. If a grantor divorced, Section 682 automatically kicked in, shifting the income tax burden away from the grantor and onto the ex-spouse who was actively receiving the distributions. It was a logical, fair mechanism.
The TCJA of 2017 repealed Section 682 entirely for divorces finalized after December 31, 2018. The official motivation was tied to the concurrent repeal of the alimony tax deduction, but the collateral damage extended far beyond simple alimony payments. With Section 682 gone, a deeply problematic federal statute known as the "Spousal Unity Rule" (IRC Section 672(e)) took absolute control.
Section 672(e) states that a grantor is treated as holding any power or interest held by an individual who was the grantor's spouse at the time the power or interest was created. Because David and Elena were married in 2014 when the SLAT was drafted, federal tax law views them as perpetually unified regarding this trust, regardless of a modern divorce decree.
Comparing the Tax Regimes: Pre-2019 vs Post-2019
The structural shift in liability is profound. The following comparison highlights the severity of the operational differences you must prepare for during divorce negotiations.
| Trust Element | Pre-2019 (Section 682 Active) | Post-2019 (Section 682 Repealed) |
|---|---|---|
| Income Tax Liability | Shifted to the ex-spouse receiving distributions. | Permanently locked to the original grantor. |
| Phantom Income Risk | Eliminated by federal law upon legal separation. | Severe. Grantor pays tax on money they cannot access. |
| Impact on Net Wealth | Equitable. The beneficiary assumes the tax burden. | Accelerated depletion of the grantor's personal assets. |
In response to the confusion this change generated, the Internal Revenue Service issued Notice 2018-37, strictly clarifying that the repeal applies to all trusts in cases of divorces executed post-2018. There are no automatic carve-outs or grandfather clauses hiding in the federal code to save you.
The Day the Reality Hit Home
The second critical moment for David arrived during a frantic phone call with his CPA and divorce attorney later that afternoon. He demanded to know how a state divorce judge could allow this to happen. The reality was bruising: state courts adjudicate the division of assets, but they cannot override federal tax law.
David’s attorney explained that because his legal team had not audited the historical structural properties of the SLAT during the stressful, combative months of discovery, the Marital Settlement Agreement (MSA) remained entirely silent on trust tax indemnification. The divorce was finalized, the ink was dry, and the court had lost jurisdiction to force Elena to reimburse David for the tax payments. Every year for the rest of his life, David would have to liquidate portions of his personal portfolio just to pay the IRS for Elena's wealth accumulation.
"Federal tax code does not care about the fairness of your divorce decree. If your settlement agreement fails to address Section 672(e), your personal wealth will be systematically dismantled by a ghost liability."
Hidden Operational Realities of Phantom Income
While the financial penalty is obvious, families and legal teams frequently overlook the operational realities of managing an adversarial grantor trust over a long time horizon. The American College of Trust and Estate Counsel (ACTEC) has repeatedly warned practitioners about these long-term frictions.
- Weaponized Trusts: A hostile ex-spouse can coordinate with a friendly trustee to maximize trust income specifically to inflate the grantor's tax liability, using the trust as a financial weapon long after the divorce.
- Failed Tax Reimbursement Clauses: Many modern trusts include a clause allowing the trustee to reimburse the grantor for taxes paid on trust income. However, these are typically discretionary. An independent trustee may refuse to distribute funds back to the grantor if they feel their fiduciary duty is strictly to the ex-spouse.
- Cash Flow Liquidation Crises: If the grantor's primary assets are tied up in illiquid businesses or real estate, they may literally lack the cash to pay the annual tax bill generated by the ex-spouse’s trust, resulting in IRS liens and compound interest penalties.
Common Mistakes Divorcing Grantors Make
Navigating the post-TCJA landscape requires avoiding a series of highly predictable pitfalls that catch high-net-worth individuals off guard.
- Trusting Boilerplate Settlement Language: Relying on standard divorce templates that state "each party is responsible for their own taxes." This does not legally mitigate the Spousal Unity Rule under federal IRS guidelines.
- Waiting Until Discovery Begins: Attempting to locate and analyze complex trust agreements, amendments, and tax returns while simultaneously fielding discovery requests from opposing counsel. This rushed environment leads to fatal analytical errors.
- Misjudging Trust Decanting Limitations: Assuming a trustee can simply "decant" (transfer) the assets into a new trust that excludes the ex-spouse. If the ex-spouse has vested rights, decanting without their consent usually triggers intense, costly litigation.
- Ignoring Capital Gains Exposure: Forgetting that grantor trust status applies to capital gains as well as ordinary income. If the trust sells a massive foundational asset post-divorce, the grantor could owe hundreds of thousands in capital gains taxes instantly.
A Strategic Framework for Surviving the Section 682 Repeal
To prevent becoming a case study like David, you must take proactive control of your estate documentation before the first divorce petition is ever filed. The following framework provides the operational steps required to secure your financial future.
- Document Consolidation and Vaulting: Locate the original trust formation agreements, all subsequent amendments, and the last three years of K-1 schedules. Secure them in an encrypted, permissioned environment separate from shared marital file storage systems.
- Sub-Trust Analysis Execution: Have a specialized estate attorney—not just a divorce attorney—review the language for "floating spouse" provisions, discretionary tax reimbursement clauses, and decanting permissions.
- Quantify the Tax Drag: Work with a forensic CPA to calculate the maximum potential tax liability the trust could generate over the next 10, 20, and 30 years based on historical asset yield.
- Negotiate Mandatory Indemnification: Ensure your Marital Settlement Agreement explicitly mandates that the ex-spouse (or the trust itself) will reimburse you annually for all income and capital gains taxes directly attributable to the trust.
- Pursue Trust Modification: If state law permits, negotiate a formal trust modification or non-judicial settlement agreement alongside the divorce, thereby formally terminating the ex-spouse's beneficial interest in exchange for other marital assets.
Executing this framework correctly requires absolute discretion and operational security. Before you alert your spouse to an impending separation, you must securely organize your estate plans and share them with the appropriate legal specialists. Utilizing Cipherwill enables you to securely upload, organize, and permission access to your trust documents within an encrypted vault. This ensures your attorneys can audit your trust architecture privately, catching vulnerabilities like the Section 682 repeal before you step into the legal crossfire.
Frequently Asked Questions (FAQ)
Question: What was IRC Section 682?
Answer: Internal Revenue Code Section 682 was a tax provision that shifted the tax liability of a grantor trust away from the creator and onto an ex-spouse following a divorce or legal separation, ensuring the person receiving the money paid the taxes.
Question: When did the repeal of Section 682 take effect?
Answer: The repeal came into effect via the Tax Cuts and Jobs Act of 2017 and applies to any divorce or separation instrument executed after December 31, 2018. Older divorces generally remain grandfathered under previous rules.
Question: What is the Spousal Unity Rule?
Answer: Found in IRC Section 672(e), this rule dictates that a trust grantor is treated as holding any power or interest held by someone who was their spouse at the exact time the trust was created, regardless of future marital status.
Question: Can a state divorce judge order the IRS to change the tax status?
Answer: No. State family courts have jurisdiction over asset division but cannot override federal tax law. A state judge cannot compel the IRS to release you from grantor trust tax liabilities, though they can order the ex-spouse to reimburse you.
Question: Does a Marital Settlement Agreement (MSA) solve the tax problem?
Answer: An MSA does not change federal tax law. However, a properly drafted MSA can mitigate the damage by legally mandating that the ex-spouse or the trust must annually reimburse the original grantor for all taxes incurred by the trust.
Question: What is a floating spouse provision?
Answer: It is a trust clause defining the beneficiary as the person to whom the grantor "is currently married," rather than naming a specific individual. In a divorce, the ex-spouse ceases to be a beneficiary, often resolving the phantom tax issue immediately.
Question: Can we simply dissolve an irrevocable trust during a divorce?
Answer: Dissolving an irrevocable trust is exceedingly complex and usually requires the consent of all beneficiaries (including the ex-spouse and potentially future children) as well as approval from a state court, which can be highly combative.
Question: Why is securing trust documents before a divorce critical?
Answer: If adversarial proceedings begin, accessing financial records can become incredibly difficult. Securing these using encrypted solutions like Cipherwill ensures your estate team can model tax exposures before the opposing counsel locks down access.
By Cipherwill Editorial Team, Reviewed by Cipherwill Review Board, Trust & Security Review Team
Editorial contributor: Myra Senapati
Review contributor: Tavish Bhonsle