

Identifying hidden assets in an estate requires moving far beyond basic paper trails to systematically decrypt what modern legal professionals call a "blind portfolio"—a collection of digital businesses, fractional shares, and tokenized holdings that solely exist online. When attempting to track family wealth, uninformed heirs frequently run into a severe legal roadblock known as the owner opinion rule. Ordinarily, property owners can legally testify to the value of their own assets without hiring formal appraisers. However, when an owner dies leaving behind undocumented, unseen wealth, their heirs lack the inherent, operational knowledge required to validate valuations for probate courts and tax authorities. Resolving this crisis requires proactive digital asset management after death, ensuring executors have both cryptographic access and the historical context legally required to claim the estate.
The Discovery: Navigating the Blind Portfolio
Consider the operational reality of Marcus, a 42-year-old digital entrepreneur who built a highly diversified, modern investment portfolio. When he passed away unexpectedly, he left behind a legally flawless traditional will. He designated his sister, Claire, as his executor, assuming that organizing legal documents for family members was merely a matter of filing standard courthouse paperwork.
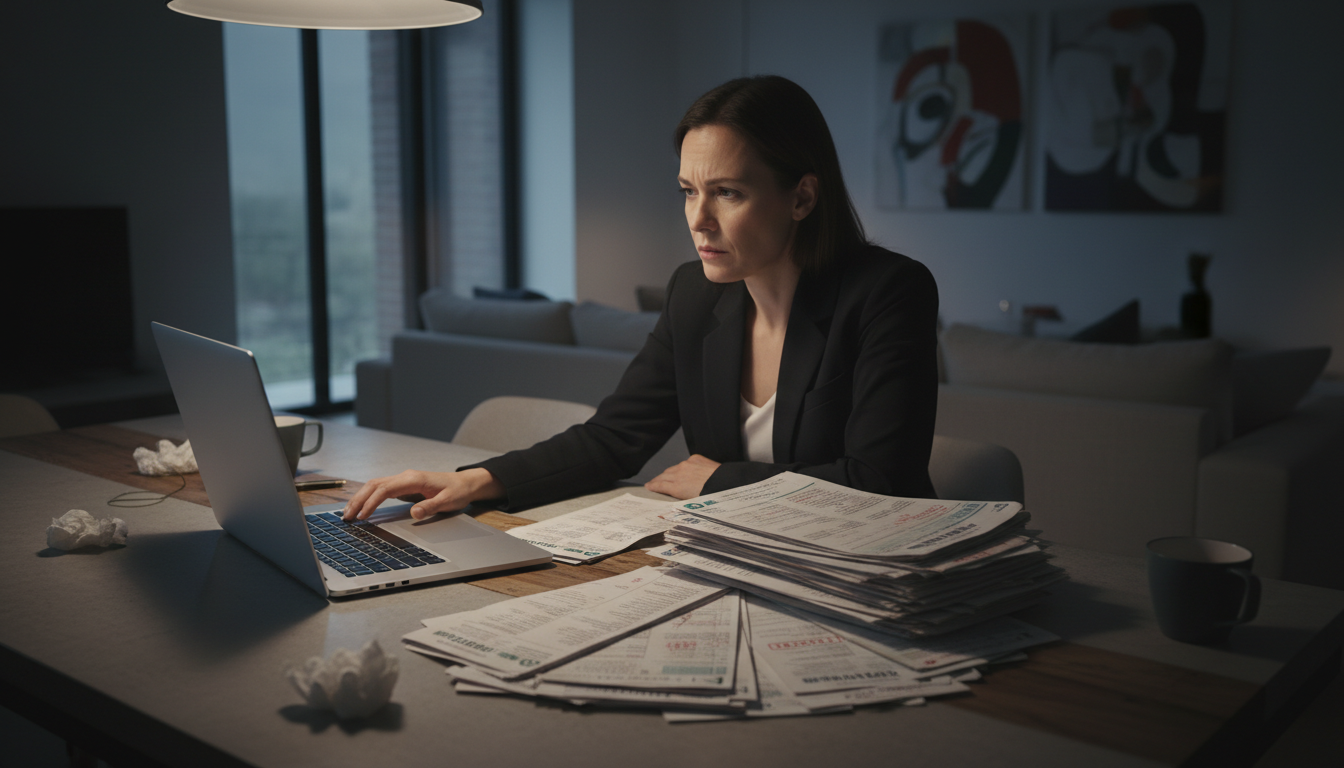
Marcus’s traditional checking accounts were instantly located and frozen by local branch managers. However, over eighty percent of his actual net worth was completely invisible. He possessed a robust blind portfolio comprising staked cryptocurrency on decentralized exchanges, fractional real estate holdings dispersed across private equity platforms, and revenue-generating domain names. Because none of these platforms generated physical mail, Claire stepped into a terrifying information void.
Claire sat at Marcus’s pristine oak desk, holding a stainless steel hardware wallet she discovered in a secondary drawer. The sleek device held no identifying marks, no brand name, and no digital interface. It was completely silent. Without the recovery seed phrase, the operational PIN, or an estate planning asset inventory to contextualize it, she realized she wasn't looking at a key to her brother's wealth—she was looking at a permanent digital tombstone.
The Legal Trap: Deciphering the Owner Opinion Rule
The breakdown in modern wealth transfer does not just stem from missing passwords; it is deeply rooted in how the legal system views asset valuation. In traditional property law, courts rely heavily on the evidentiary presumption that an owner inherently understands the value of their possessions.
Under federal and state evidentiary standards, such as Federal Rules of Evidence Rule 701, an owner is generally permitted to offer lay opinion testimony regarding the value of their property without retaining specialized, expert credentials. They know the property’s quirks, its history, and its fair market standing. But when the owner passes away, this structural convenience vanishes.
"The estate executor steps into the legal shoes of the deceased, but without a documented operational history, they inherit the liability of the assets without any of the legal credibility required to appraise them."
When Claire attempted to file an official IRS Form 706 to determine estate taxes, the bureaucratic machinery halted. Because the assets were entirely digital and unseen, she possessed zero operational context. She could not legally testify to the fluctuating value of a specialized decentralized finance protocol at the exact Date of Death (DoD) because she had zero familiarity with it. Consequently, the probate court rejected her good-faith estimates. She was forced into an agonizingly expensive corner, forced to bleed estate capital by hiring forensic digital appraisers to legally establish what Marcus already knew.
Traditional Wealth vs. Digital Asset Discovery
To truly understand identifying hidden assets in an estate, it helps to meaningfully contrast the legacy model of estate administration against modern digital realities. Historically, “how to track family wealth” translated to intercepting the deceased’s mail for three months. Bank statements, tax forms, and dividend checks would inevitably arrive, painting a complete financial picture.
Digital assets intentionally bypass this entire discovery mechanic. Fractional real estate accounts, software-as-a-service businesses, and centralized exchange accounts default to completely paperless delivery, protected by two-factor authentication loops that lock out unauthorized physical hardware.
Operational Valuation Obstacles
| Asset Classification | Primary Valuation & Discovery Obstacle |
|---|---|
| Decentralized Cryptocurrencies | No central custodian to report balances. Complete reliance on self-custody hardware keys and immediate market volatility upon date of death. |
| Fractional Real Estate & Private Equity | Paperless accounts with strict non-transferability clauses. Inherently difficult to appraise on the secondary market without formal platform access. |
| Monetized Digital Identities (e.g., Software, Media) | Value is heavily tied to operational continuity. Prolonged administrative probate freezes can actively destroy the asset's underlying revenue generation value. |
The Cascading Consequences of Undocumented Holdings
Leaving behind a blind portfolio triggers a severe operational cascade that rarely resolves itself quietly. Beyond the emotional burden placed on grieving families, the financial and regulatory consequences are aggressively punitive.
- IRS Accuracy-Related Penalties: Misidentifying or vastly undervaluing complex wealth due to missing documentation can trigger severe penalties under IRS Section 6662. Ignorance of an asset's complexity is not an accepted defense during an estate audit.
- Forced Escheatment: If an executor cannot log into a traditional wealth platform or properly verify death with a digital brokerage, those accounts will eventually go dormant and be escheated—transferred permanently—to the state’s unclaimed property division.
- Irreversible Cryptographic Loss: The absolute lack of a central authority in blockchain architecture dictates a harsh reality: missing context equates to missing funds. A localized hard drive failure or an unrecorded twelve-word seed phrase permanently locks the wealth out of the human supply.
Common Mistakes When Building an Estate Planning Asset Inventory
Attempting to solve the blind portfolio problem through informal, fragmented means often compounds the legal jeopardy for an executor. Families routinely make critical errors when structuring their transitions.
1. Relying on Static Spreadsheets
A locally saved Excel document summarizing accounts is dangerously static. Market conditions, specific platform URLs, two-factor authentication methods, and custody protocols shift continually. By the time the estate executes, a three-year-old static spreadsheet is operationally useless and highly misleading to the probate court.
2. The Direct Password Handover Violation
Many individuals simply write their master passwords on a legal pad. However, an executor logging into a deceased person’s digital account using their live credentials structurally violates the platform's Terms of Service. More importantly, it can constitute illegal unauthorized access under federal statutes like the Computer Fraud and Abuse Act (CFAA), exposing the executor to immense personal liability during discovery.
3. Ignoring the Legislative Consent Blueprint
Without explicit, legally binding digital consent embedded in your plan, technology companies will block your heirs. The Revised Uniform Fiduciary Access to Digital Assets Act (RUFADAA) demands that platforms receive affirmative, written authorization to grant fiduciaries access to underlying communications and digital assets. Omitting this specific language forces the family into protracted, wildly expensive corporate litigation.
The Recovery Path: A Decision Framework for Your Heirs
Eliminating the reliance on the owner opinion rule requires systematic operational clarity. You must build an interactive ecosystem that provides your designated fiduciaries immediate context, legal authority, and secure technical routing.
Follow this concrete decision framework to ensure a verified, non-blind portfolio transition:
- Catalog by Custody, Not Just Value: Do not just list the monetary value of an asset. Explicitly define the custody relationship. Is it held independently on hardware, brokered through an institution, or fractionalized in a corporate trust?
- Establish the RUFADAA Authorization Tier: Ensure your core estate documents contain explicit statutory references enabling your executor to legally bypass custodial stalemates without triggering Terms of Service breaches.
- Document the Exact Valuation Mechanic: Provide the heir with the precise procedural steps for pulling historical valuation data from the specific platform interface to satisfy Form 706 Date of Death requirements.
- Implement Cryptographic Time-Release Infrastructure: Utilize localized, encrypted digital vaults that automatically verify your incapacitation before securely distributing the master inventory payload to your trustees.
Consider the stark contrast of a properly executed recovery path. Months after a well-planned passing, Claire would not be hunting for silent hardware devices. By utilizing a centralized execution protocol, Claire received an automated briefing package. Instead of hunting for loose credentials, she opened a securely decrypted vault environment that clearly mapped her brother's specific fractional real estate holdings, complete with recent valuation dashboards, exact legal account names, and precise custodial contact protocols, immediately clearing her legal roadblocks.
Implementing Digital Asset Management After Death
Identifying hidden assets in an estate should never be left to chance or informal discovery processes. Navigating the evidentiary complexities of the owner opinion rule and establishing credible market values demands institutional-grade infrastructure. This is functionally why the Cipherwill platform exists—to modernize and secure the absolute fragility of transitional wealth.
By utilizing a designated dead man’s switch integrated tightly with localized cryptographic storage environments, you move past the archaic nature of paper binders. You gain the ability to organize legal documents for your family, bind the necessary digital context, and systematically disburse decryption keys to authorized stakeholders precisely when they need them. It permanently bridges the gap between holding unseen modern wealth and ensuring your family possesses the complete operational standing to legally secure it.
Frequently Asked Questions
Question: What exactly is an estate planning asset inventory?
Answer: An estate planning asset inventory is a comprehensive, centralized record detailing the existence, location, and operational context of your physical and digital holdings. It allows an estate executor to immediately locate and value property, avoiding expensive, prolonged discovery processes during the execution of a will or trust.
Question: How does the owner opinion rule affect probate?
Answer: This legal rule generally allows a property owner to testify to their asset’s value without being a professional appraiser. When the owner dies, heirs lack this inherent familiar knowledge, forcing the estate to hire expensive forensic appraisers to legally establish the baseline value of undocumented or purely digital wealth.
Question: What constitutes a blind portfolio in estate planning?
Answer: A blind portfolio refers to a collection of invisible modern assets—such as cryptocurrency, fractional digital real estate, or online businesses—that generate no physical mail or standard tangible documentation, making them exceptionally difficult for a subsequent fiduciary or family member to independently locate.
Question: Why is organizing legal documents for family harder with digital assets?
Answer: Digital assets sit behind aggressive custodial firewalls, multi-factor authentication loops, and strict terms of service. Unlike physical property deeds stored in a secure filing cabinet, accessing digital wealth requires active, persistent technological authorization protocols that heavily resist standard post-mortem legal transfers.
Question: How to track family wealth when accounts have no paper statements?
Answer: Families must deploy dedicated digital asset management systems before a crisis occurs. By proactively establishing a localized cryptographic vault tied to a secure execution timeline, the primary asset holder explicitly defines exact operational access parameters for their beneficiaries.
Question: Does sharing passwords help with digital asset management after death?
Answer: No. Handing over direct passwords without proper legal authorization in the structural will typically violates platform Terms of Service. In some severe instances, logging in as the deceased can breach federal hacking statutes like the Computer Fraud and Abuse Act, exposing the executor to immense liability.
Question: Can the IRS issue penalties for incorrectly valuing hidden assets?
Answer: Yes. The Internal Revenue Service expects estates to accurately report fair market value on Date of Death valuations for Form 706. Severely undervaluing complex digital holdings due to missing initial documentation can actively trigger steep accuracy-related penalties under IRS Section 6662, costing the estate heavily.
By Cipherwill Editorial Team, Reviewed by Cipherwill Review Board, Trust & Security Review Team
Editorial contributor: Samarjeet Vohra
Review contributor: Ishani Debroy